5 Ways to Make Your Home Stand Out When Mortgage Rates Are High in New Jersey
When mortgage rates are high, buyers often become more selective about which homes they consider. Higher monthly payments can affect affordability, and buyers may compare properties more carefully before deciding which homes are worth seeing in person.
But that doesn't mean your home can't stand out or attract a strong offer.
The key is giving buyers a compelling reason to choose your home over the other properties available to them. That takes more than simply putting a sign in the yard, uploading photos, and waiting for an offer.
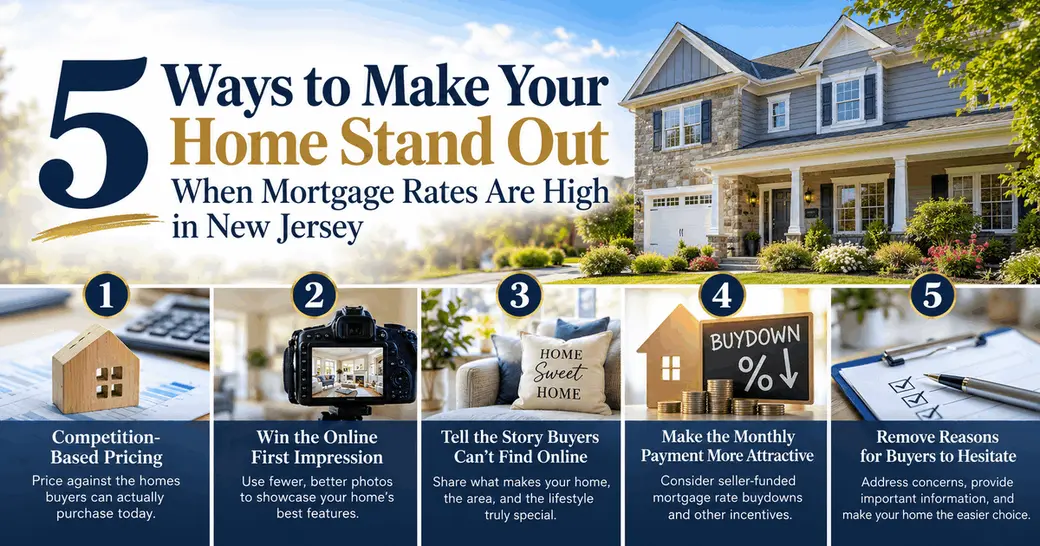
For New Jersey homeowners considering selling, here are five strategies that can help your property compete, attract attention, and create a stronger impression—even when mortgage rates are elevated.
Why Do Higher Mortgage Rates Make Selling a Home More Challenging?
Mortgage rates influence how much a buyer can afford to borrow and what their monthly housing payment may look like.
When rates rise, a buyer who previously qualified comfortably for a particular price range may find that the same home now costs significantly more each month.
Some buyers adjust their budgets. Others become more selective about property condition, location, features, and overall value.
According to Freddie Mac, the average 30-year fixed mortgage rate was 7.40% as of October 15, 2026, compared with 6.27% one year earlier. Mortgage rates change frequently, and individual borrowers may receive different rates depending on their financing circumstances.
Source: Freddie Mac Primary Mortgage Market Survey.
For sellers, the lesson isn't necessarily to wait for rates to fall. It's to understand what today's buyers are comparing and develop a strategy that makes your home an attractive choice.
1. Use Competition-Based Pricing: Price Against the Homes Buyers Can Actually Purchase
One of the most important decisions when selling a home is establishing the right asking price.
Most homeowners and real estate agents begin by looking at comparable homes that have recently sold. Those closed sales are important because they provide evidence of what buyers have been willing to pay and help establish a market-supported price.
But there's another part of pricing that deserves just as much attention: the homes actively for sale when your property enters the market.
Closed Sales Tell You What Happened. Active Listings Show You Today's Competition.
Imagine you're preparing to list your home for $675,000.
Recent comparable sales may suggest that $675,000 is a reasonable asking price. But what if three similar homes are currently available nearby?
- Home A is listed for $659,000 and has an updated kitchen.
- Home B is listed for $675,000 and offers a finished basement.
- Home C is listed for $689,000 and has a larger lot and newer mechanical systems.
These are hypothetical examples, but they illustrate an important question:
Why would a buyer choose your home over the other homes they can purchase right now?
A buyer shopping online isn't limited to reviewing past sales. They're comparing your home against other properties they can schedule appointments to see this weekend.
That's why we believe a strong pricing strategy should consider both recent closed sales and current active competition.
Make Your Home the Better Value, Not Necessarily the Cheapest Home
Competition-based pricing doesn't mean automatically underpricing your property.
It means understanding how buyers are likely to compare homes based on price, condition, location, layout, updates, and overall appeal.
A home priced slightly higher may still offer better value if it has meaningful advantages. Conversely, a home with fewer updates or less desirable features may need to be positioned more competitively.
The goal is to create a situation where buyers recognize the value of your home relative to their other choices.
There is no guarantee that a particular price will produce showings or offers. However, strong competitive positioning can improve the likelihood that buyers include your home on their shortlist.
Our advice: Before choosing an asking price, review the homes your potential buyers will be comparing against yours. Then ask whether your property offers a compelling reason to schedule a showing.
For additional guidance, read our article on how to price your home correctly in New Jersey.
2. Win the Online First Impression: Sometimes Fewer, Better Photos Are More Effective
For many buyers, their first impression of your home happens long before they walk through the front door.
It happens on a phone, tablet, or computer while browsing real estate listings.
According to the National Association of REALTORS®, 81% of buyers surveyed in its 2025 Profile of Home Buyers and Sellers considered listing photos a very useful feature during their online home search.
Source: National Association of REALTORS® — How to Maximize Online Visibility for Every Listing.
That makes the quality and presentation of your listing photos extremely important.
More Photos Don't Automatically Mean Better Marketing
Some sellers assume that if a home has 40 rooms, corners, closets, hallways, and angles worth photographing, every one of them should appear online.
But buyers don't necessarily need to see every inch of your property before deciding whether to schedule a showing.
Too many repetitive or poorly selected photographs can make a home feel less appealing or harder to understand.
For example, five nearly identical photos of the same bedroom may add little value. An awkward angle of a hallway or an unnecessary close-up of a minor cosmetic issue may distract from the home's strongest features.
Our philosophy is to use enough excellent photographs to tell the home's story clearly, rather than assuming the largest possible photo collection is the best approach.
This doesn't mean hiding material defects, misrepresenting rooms, or leaving buyers with an inaccurate understanding of the property. Accurate photography and required disclosures remain essential.
Every Photo Should Have a Purpose
A well-planned photo collection should help buyers understand:
- The home's exterior appearance and curb appeal
- The most attractive living spaces
- The layout and flow between important rooms
- The kitchen, bathrooms, and bedrooms
- Outdoor living areas and other meaningful features
- Any distinctive spaces that set the property apart
Professional lighting, thoughtful composition, appropriate photo order, and accurate representation can make a substantial difference in how buyers perceive a listing.
Floor plans and virtual tours can also provide helpful layout information without requiring dozens of repetitive photographs.
The goal is simple: give buyers enough information to become genuinely interested, then make them want to experience the home in person.
3. Tell the Story Buyers Can't Find Online: Market the Lifestyle, Not Just the Specifications
Most real estate websites already provide the basic facts about a property.
Buyers can usually see the number of bedrooms, bathrooms, approximate square footage, lot size, property taxes, and other listing details.
Those facts are important, but simply repeating them in the property description doesn't necessarily give buyers a new reason to become interested.
Consider the difference between these two approaches:
Basic description: "Three-bedroom, three-bath home with a finished bonus room and convenient location."
More informative description: "The flexible bonus room has worked beautifully as a home gym, while a convenient route out of the neighborhood provides quick access to nearby major highways."
The second description gives the buyer something more useful to imagine and investigate.
It helps explain how the property might fit their everyday needs.
What Made You Fall in Love With Your Home?
Think back to when you first purchased your home.
What attracted you to it?
More importantly, what have you discovered about living there that you didn't fully appreciate until after moving in?
Perhaps you learned that:
- A particular route out of the development provides convenient access to a major highway.
- A bonus room makes an excellent home gym, office, craft room, or hobby space.
- The backyard layout works particularly well for outdoor entertaining.
- The kitchen layout makes everyday meal preparation easier than you expected.
- A nearby park, shopping area, or walking trail has become part of your routine.
- A covered porch or deck provides an enjoyable outdoor space during different seasons.
- A particular storage area or flexible room is far more useful than it initially appeared.
These details may not be obvious from an online listing, yet they can help a buyer understand what makes the property special.
The things that made you appreciate living in your home may be exactly what helps another buyer connect with it.
The 10-Minute Conversation Every Seller Should Have With Their Listing Agent
Before your home goes on the market, we recommend setting aside at least 10 minutes to discuss what makes your property different from the others buyers will be considering.
This conversation should go beyond the usual questions about bedroom counts, bathrooms, and recent improvements.
Here are 10 questions worth discussing with your listing agent:
- What originally attracted you to this home? Was it the layout, location, outdoor space, or something else?
- What have you come to appreciate most about living here? Think about conveniences you didn't recognize before moving in.
- Which room or space has been more useful than you expected? Perhaps a bonus room became a gym, office, or creative workspace.
- What features make everyday living easier? Consider storage, parking, access, layout, and other practical advantages.
- What do you enjoy about the surrounding area? Think about parks, shopping, restaurants, transportation routes, and nearby amenities.
- What improvements have you made, and why? Explain the practical benefits, not just the work completed.
- What might buyers overlook during a quick showing? Some of a home's best features aren't immediately obvious.
- How have you used the outdoor spaces? Consider patios, decks, gardens, and flexible entertaining areas.
- What do visitors frequently compliment? Outside perspectives can reveal features you've come to take for granted.
- If you were buying this home again, what would you most want to know? This can reveal the details that deserve attention in the marketing.
For example, simply saying "new roof installed" communicates a useful improvement.
But explaining that the roof was replaced recently, providing the available warranty information, and sharing documentation of the work gives buyers a clearer understanding of the improvement.
Likewise, saying a property is "conveniently located" is generic. Identifying a nearby highway entrance, train station, or shopping area provides information buyers can independently verify.
Travel times should be presented accurately and should not be guaranteed because traffic and conditions change.
Property descriptions should focus on the home's features, location, and amenities—not assumptions about the type of person or family who should live there. All marketing should comply with fair housing requirements.
Our advice: Give your agent the complete story of your home. The more relevant, accurate information they have, the better equipped they are to highlight what makes your property distinctive.
4. Make the Monthly Payment More Attractive: Consider Seller-Funded Mortgage Rate Buydowns
When mortgage rates are elevated, one of the biggest concerns for buyers is often the monthly payment.
That creates an opportunity for sellers to consider incentives beyond a traditional price reduction.
One option is offering a seller concession toward eligible buyer closing costs, including a mortgage interest rate buydown when permitted by the buyer's financing program.
What Is a Seller-Funded Mortgage Rate Buydown?
A mortgage rate buydown is a financing arrangement designed to reduce the interest cost or payment a borrower experiences, either temporarily or over the life of the loan.
Two common approaches are temporary buydowns and permanent buydowns.
Temporary Mortgage Rate Buydowns
A temporary buydown, such as a 2-1 buydown, uses funds deposited through an approved arrangement to subsidize part of the buyer's mortgage payments during an initial period.
For example, with a 7% fixed note rate, an illustrative 2-1 buydown could provide payments calculated using an effective 5% rate during the first year and 6% during the second year. Beginning in the third year, the borrower makes the full payment based on the 7% note rate.
The mortgage note itself still carries the 7% rate throughout the loan term. The temporary subsidy does not permanently change the loan's interest rate.
For qualifying loans under Fannie Mae guidelines, the buyer must qualify using the full note rate rather than the temporarily reduced payment.
Permanent Mortgage Rate Buydowns
A permanent buydown typically involves paying eligible discount points to obtain a lower mortgage interest rate for the loan's term.
The actual rate reduction depends on the lender, available pricing, loan program, and market conditions.
For some buyers, a permanent reduction may be more attractive than a temporary payment subsidy because it can provide savings beyond the first few years, assuming the loan remains in place.
Example: Seller Concession Versus Price Reduction on a $650,000 Home
Let's assume a home is listed for $650,000 and the buyer plans to make a 20% down payment with a 30-year fixed mortgage.
At an illustrative 7% interest rate, the buyer's $520,000 mortgage would have a monthly principal and interest payment of approximately $3,460.
Now consider two hypothetical options:
- Option A: $10,000 price reduction. The sale price drops to $640,000. With 20% down and the same 7% interest rate, the buyer's mortgage would be $512,000, with principal and interest of approximately $3,406 per month.
- Option B: $10,000 seller concession. The price remains $650,000, but the seller agrees to contribute up to $10,000 toward eligible financing costs. Depending on the lender's available programs, some or all of that amount might help fund a mortgage rate buydown.
In this simplified example, the $10,000 price reduction lowers principal and interest by approximately $53 per month.
A qualifying mortgage rate buydown may provide a different payment benefit, potentially making the concession more attractive to a buyer focused on monthly affordability.
However, the exact benefit cannot be determined without a lender's quote. A $10,000 concession does not guarantee a particular interest rate or payment reduction.
The seller must also evaluate net proceeds, appraisal considerations, and the buyer's financing requirements. A seller concession is not automatically better than a price reduction.
Important Rules for Seller Concessions
Seller concessions and mortgage rate buydowns are subject to lender approval and loan-program restrictions.
For example, Fannie Mae has limits on interested-party contributions that vary by occupancy type and loan-to-value ratio. Eligible seller-funded temporary and permanent rate buydowns generally count toward those limits.
Some loan programs or transaction types may not permit certain buydown arrangements.
Before advertising a specific financing incentive, sellers should work with their real estate agent and a qualified mortgage professional to confirm what is available and how it affects the transaction.
For more information, review Fannie Mae's Interested Party Contributions guidance and Temporary Interest Rate Buydown requirements.
Our advice: Don't assume a price reduction is your only option when buyers are concerned about affordability. Ask whether a carefully structured seller concession could help your home compete while supporting your financial goals.
5. Remove Reasons for Buyers to Hesitate: Make Your Home the Easier Choice
When buyers are already concerned about higher mortgage payments, the possibility of unexpected expenses can become an even bigger obstacle.
A home that appears well maintained, provides useful documentation, and is easy to evaluate may feel more attractive than a competing property with unanswered questions.
Address Obvious Concerns Before Buyers Discover Them
Before listing, walk through the property with your agent and identify issues that could create unnecessary hesitation.
Examples might include:
- Minor repairs that are inexpensive to complete
- Visible maintenance issues
- Unfinished cosmetic projects
- Clutter that makes rooms difficult to appreciate
- Missing information about major improvements
- Unclear permits, warranties, or service records
Not every issue needs to be repaired before selling, and major projects should be evaluated carefully.
But addressing manageable concerns can help buyers focus on the home's strengths instead of immediately calculating additional costs.
Provide Helpful Information Up Front
Buyers may appreciate knowing when important components were updated, what warranties may be transferable, and whether documentation is available.
For example, if you replaced the roof, upgraded the HVAC system, or completed a major renovation, gather available invoices, permits, warranties, and other relevant records.
This information doesn't replace inspections or required disclosures, but it can help buyers better understand the property.
Make It Easy for Qualified Buyers to See the Home
Even excellent pricing and marketing can be less effective when a home is difficult to show.
Reasonable showing flexibility, clear access instructions, and timely responses to inquiries can help interested buyers evaluate the property while their interest is strongest.
Our advice: Buyers don't necessarily expect perfection. They want to understand what they're purchasing, what it may cost them, and whether the home offers the right combination of value and features.
How Do You Know Which Selling Strategies Are Right for Your Home?
Every home and every local market is different.
A strategy that works for a renovated home in Metuchen may not be the right approach for an older property in Woodbridge, a townhouse in Edison, or a single-family home elsewhere in Middlesex or Union County.
The best approach depends on several factors:
- Current competing inventory
- Recent comparable sales
- Property condition and presentation
- Price range and buyer demand
- Available marketing opportunities
- The seller's timeline and financial priorities
At The Egri Team, we believe the most effective listing strategy begins with understanding how your property compares with the alternatives buyers have today.
From there, we can evaluate how pricing, photography, property storytelling, targeted marketing, and potential financing incentives may work together.
For additional preparation ideas, explore our New Jersey Home Seller's Guide.
Thinking About Selling Your Home in New Jersey?
Higher mortgage rates don't mean you have to put your plans on hold. They do mean that positioning your home effectively may be more important than ever.
Before deciding on an asking price, we'd welcome the opportunity to show you how your property compares with the homes currently competing for buyers' attention.
We can also discuss which features deserve the spotlight, how to present your home online, and whether seller incentives might make sense for your situation.
Our goal is to help you make informed decisions about pricing and marketing while working toward the strongest possible outcome for your sale.
Contact The Egri Team to Discuss Your Home Selling Strategy
You can also begin by exploring what your home may be worth in today's market.
Frequently Asked Questions About Selling When Mortgage Rates Are High
Is it harder to sell a house when mortgage rates are high?
Higher mortgage rates can reduce purchasing power and make some buyers more selective. However, selling conditions vary by location, property type, price range, and available inventory. Competitive pricing and effective marketing can help a home attract attention even when financing costs are elevated.
Should I lower my asking price because mortgage rates are high?
Not automatically. Review recent comparable sales, active competing listings, buyer activity, and your home's condition before deciding whether a price adjustment is appropriate.
Are active listings more important than recently sold homes when pricing?
Both are important. Closed sales provide evidence of market value, while active listings show the alternatives buyers can currently purchase. An effective pricing strategy considers both, along with pending sales and current market conditions.
Should I include as many photos as possible in my home listing?
Not necessarily. A carefully selected collection of accurate, high-quality photographs can communicate a home's strongest features more effectively than numerous repetitive images. Buyers should still receive a truthful representation of the property.
What information should I share with my listing agent?
Share the home's improvements, practical conveniences, distinctive spaces, nearby amenities, and details you've appreciated while living there. This information can help your agent create more informative marketing materials.
Can a seller pay to lower a buyer's mortgage rate?
In some transactions, yes. Seller concessions may be used toward eligible temporary or permanent mortgage rate buydowns, subject to the buyer's loan program, lender approval, contribution limits, and other requirements.
Is offering a mortgage rate buydown better than reducing the price?
It depends on the buyer's financing, the cost of the buydown, the appraisal, and the seller's net proceeds. A lender can compare the potential payment benefits, while the listing agent can help evaluate the overall offer and market strategy.
How can I make my home stand out from competing listings?
Focus on competition-based pricing, compelling online presentation, meaningful property details, appropriate buyer incentives, and reducing unnecessary concerns that might prevent buyers from moving forward.
This article is provided for general educational purposes and does not constitute financial, mortgage, tax, or legal advice. Mortgage rates, loan qualifications, seller concession limits, and buydown availability vary by lender and loan program. Illustrative payment examples exclude property taxes, homeowners insurance, mortgage insurance, HOA fees, and other expenses. Consult qualified real estate, mortgage, legal, and financial professionals regarding your specific circumstances.
Recent Posts