5 Red Flags NJ Home Sellers Should Watch for Before Accepting an Offer
Receiving an offer on your home is exciting. After preparing your property, scheduling showings, and waiting for the right buyer, seeing an offer in writing can feel like a major step toward your next move.
But before you celebrate the purchase price, there's an important question every New Jersey homeowner should ask:
How confident are we that this buyer can actually close—and what will we walk away with?
An attractive offer can sometimes contain financing concerns, appraisal risks, unexpected expenses, or contract terms that deserve a closer look.
That doesn't necessarily make it a bad offer. It means you should understand the potential risks before deciding whether to accept, reject, or negotiate.
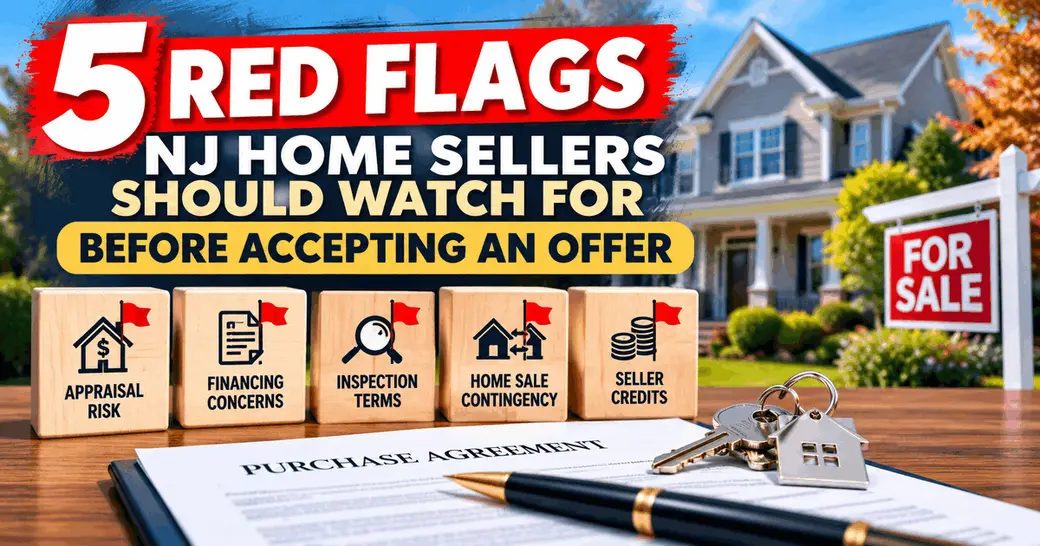
Here are five red flags New Jersey home sellers should watch for before accepting an offer.
What Are the Biggest Red Flags in a Home Buyer's Offer?
Five important warning signs include an offer price that may not appraise, financing that hasn't been thoroughly reviewed, uncertain inspection terms, a purchase dependent on another home sale, and seller concessions or closing terms that reduce your actual proceeds.
None of these factors automatically disqualifies a buyer. The key is to evaluate the complete offer rather than focusing exclusively on the price.
1. The Buyer Offers Well Above Asking Price Without a Clear Appraisal Plan
Imagine listing your home in Edison for $700,000 and receiving an offer for $750,000.
At first glance, that's exciting. But what happens if the buyer is obtaining a mortgage and the property appraises for less than the agreed purchase price?
Depending on the financing and contract terms, a low appraisal could create a funding gap that needs to be resolved before closing.
The buyer may need additional available funds, the parties may negotiate a different price or arrangement, or the transaction could be affected under applicable contract provisions.
What Sellers Should Ask
- Does the proposed price align with recent comparable sales?
- How much is the buyer planning to put down?
- Does the buyer have documented funds available if the appraisal is lower?
- What does the contract say about appraisal and financing contingencies?
- Has the buyer agreed to any specific appraisal-gap terms?
The red flag isn't simply a high offer. It's a high offer without a realistic plan to support the purchase price.
An experienced listing agent can help evaluate comparable sales and identify questions that should be addressed before accepting the offer.
2. The Buyer's Mortgage Preapproval Raises Unanswered Questions
A mortgage preapproval can be an important part of a buyer's offer, but it is not a guarantee that the mortgage will be approved.
Lenders vary in how thoroughly they review income, assets, credit, and other information before issuing a preapproval letter.
Some preapprovals involve substantial documentation and review. Others may be based on more limited information.
According to the Consumer Financial Protection Bureau, the terms "prequalification" and "preapproval" are not used consistently across lenders, and neither automatically guarantees financing.
Questions Worth Reviewing
- Is the preapproval current?
- Does the proposed financing appear consistent with the purchase price?
- Has the lender reviewed relevant financial documentation?
- Does the buyer need proceeds from another property to complete the purchase?
- Are there unusual financing conditions or timing concerns?
Your listing agent may be able to discuss general financing readiness and transaction requirements with the lender, subject to the buyer's authorization and applicable privacy requirements.
Remember: A buyer with a smaller down payment is not automatically less qualified than a buyer with a larger down payment. Financing strength depends on the complete situation, not one number.
3. The Inspection Terms Leave Too Much Uncertainty
Home inspections are a normal and important part of many New Jersey real estate transactions.
However, sellers should carefully review the inspection language in an offer rather than assume all inspection contingencies work the same way.
For example, an offer may leave questions about:
- Which inspections the buyer intends to conduct
- The deadlines for completing inspections
- What types of issues may lead to repair or credit requests
- How inspection disputes will be handled
- What rights each party has if an agreement cannot be reached
Why This Matters
Imagine accepting a strong offer on your home in Woodbridge.
After inspections, the buyer requests a substantial credit for several items that were visible during the initial showing.
Whether those requests are permitted, negotiable, or grounds for further action depends on the actual contract and applicable law.
The concern for sellers is not that buyers conduct inspections. It's that unclear expectations can create conflict after the home is under contract.
Before accepting an offer, have your attorney review the inspection provisions so you understand your obligations and the buyer's rights.
For additional information, read our article What Repairs Are Sellers Required to Make in New Jersey?.
4. The Buyer Must Sell Another Home Before Purchasing Yours
Some buyers need to sell their current property before purchasing their next home.
This is a common situation and does not automatically make the buyer unreliable.
However, a home-sale contingency can introduce additional steps and uncertainty into your transaction.
For example, a buyer purchasing your home in East Brunswick may need to close on their existing home before they have the funds required for your sale.
If their sale is delayed, your closing may also be affected.
Important Questions to Ask
- Is the buyer's current home already listed?
- Is it under contract?
- Has the buyer's purchaser obtained mortgage approval?
- Are there unresolved contingencies on that transaction?
- Does the buyer have another acceptable way to complete your purchase if their sale is delayed?
Consider two buyers who both offer $725,000.
One has a home to sell but hasn't listed it yet.
The other has already sold their property and has the necessary funds available.
The offers may look identical in price, but their timelines and dependencies are different.
That doesn't mean the second buyer must be selected. It means the first offer deserves a careful review of the contingency and supporting circumstances.
For sellers who are also purchasing another property, these details can be especially important.
Related reading: How to Buy and Sell a House at the Same Time in New Jersey.
5. The Offer Price Looks Great, but Credits and Contract Terms Reduce Your Proceeds
One of the most important numbers in a home sale isn't the offer price.
It's the amount you expect to receive after the agreed transaction expenses, concessions, mortgage payoff, and other applicable costs.
Buyers may request seller contributions toward eligible closing costs, financing expenses, or other negotiated terms.
Those requests aren't inherently unreasonable. But sellers should understand their financial impact.
Example: Two Offers on a $750,000 Listing
Suppose you're selling your home in Middlesex County and receive these two hypothetical offers:
| Offer detail | Buyer A | Buyer B |
|---|---|---|
| Purchase price | $750,000 | $735,000 |
| Requested seller credit | $20,000 | $0 |
| Price minus requested credit | $730,000 | $735,000 |
| Financing and appraisal terms | Require further review | Require further review |
| Closing timeline | To be evaluated | To be evaluated |
Even though Buyer A offers $15,000 more, the requested $20,000 seller credit leaves $5,000 less before considering other expenses.
This simplified comparison does not represent a complete seller net proceeds statement. Actual proceeds depend on the final contract, mortgage payoff, transfer fees, commissions, prorations, closing expenses, and other transaction-specific factors.
Seller contributions must also satisfy the buyer's mortgage program requirements.
The lesson: Compare the financial and contractual terms of each offer—not just the headline price.
For more information about seller expenses, read How Much Does It Cost to Sell a House in New Jersey?.
How to Compare Multiple Offers on Your New Jersey Home
When multiple offers arrive, a structured comparison can help sellers make a more informed decision.
Here are several factors worth reviewing with your agent and attorney:
| What to compare | Why it matters |
|---|---|
| Purchase price | Shows the amount the buyer proposes to pay |
| Seller credits | Can reduce the seller's proceeds |
| Financing | Helps assess mortgage-related conditions and timing |
| Appraisal terms | Clarifies how a valuation shortfall may affect the sale |
| Inspection provisions | Defines important rights, deadlines, and possible negotiations |
| Home-sale contingency | May introduce dependence on another transaction |
| Closing date | Should align with your moving and financial plans |
| Other contract terms | May affect costs, obligations, or the likelihood of closing |
The strongest offer for one seller may not be the strongest offer for another.
A homeowner who needs a predictable closing date may value different terms than a seller who has already moved and can accommodate a longer timeline.
Does a Higher Offer Always Mean More Money for the Seller?
No. A higher purchase price does not always produce higher net proceeds or a smoother closing.
Seller credits, financing conditions, appraisal issues, contingencies, and closing expenses can change the financial outcome.
For example, a $750,000 offer with a $20,000 seller credit can provide less before other expenses than a $735,000 offer with no credit.
That is why sellers should request a side-by-side review of the actual terms before making a decision.
What Happens After You Accept an Offer in New Jersey?
In New Jersey, the next steps depend on the contract and circumstances.
Many residential transactions involving broker-prepared contracts include an attorney review period. During that process, the attorneys may review and negotiate contract provisions.
The parties must also address applicable financing, inspection, appraisal, title, and closing requirements.
An accepted offer is an important milestone, but it does not mean every condition required for closing has already been satisfied.
For more information, visit our step-by-step guide to selling a house in New Jersey.
How The Egri Team Helps Sellers Evaluate Offers
At The Egri Team, we believe sellers deserve more than a quick explanation of the purchase price.
When evaluating an offer, we help our clients understand the proposed terms, consider the property's market value, and identify questions that should be addressed before moving forward.
We work with homeowners throughout Middlesex County, Union County, and surrounding New Jersey communities, including Woodbridge, Edison, Metuchen, East Brunswick, Sayreville, and neighboring towns.
Our goal is to help sellers make informed decisions while coordinating with their attorney, lender, and other professionals as appropriate.
That includes discussing:
- The offer's price compared with relevant market data
- Requested seller concessions and their financial impact
- Financing and appraisal considerations
- Inspection and other contractual contingencies
- Proposed closing and occupancy arrangements
- How the terms fit your plans for your next move
Thinking About Selling Your Home in New Jersey?
You don't have to wait until you receive an offer to start planning how you'll evaluate one.
Understanding your home's current market value, your likely selling expenses, and your priorities can help you prepare for negotiations before your property goes on the market.
If you're considering selling, we'd be happy to discuss your property and help you understand your options.
Find Out What Your Home May Be Worth
Or contact Chris & Diane Egri to schedule a conversation about your selling plans.
Frequently Asked Questions About Home Buyer Offer Red Flags
Should I accept the highest offer on my house?
Not necessarily. Review the purchase price together with financing, contingencies, requested credits, closing dates, and other contract terms. The highest price may not provide the best overall financial or practical outcome.
Is a mortgage preapproval a guarantee that a buyer can close?
No. A preapproval generally indicates that a lender is tentatively willing to provide financing based on certain information and assumptions. Final loan approval depends on additional requirements.
What happens if my house appraises below the offer price?
The outcome depends on the financing and contract terms. The buyer may need additional funds, the parties may negotiate, or contractual rights may affect whether the transaction proceeds.
Is an offer with a home-sale contingency a bad offer?
Not automatically. Many buyers need to sell another home first. Sellers should understand the contingency, the status of the buyer's existing sale, and the potential effect on closing.
Can a seller reject an offer asking for closing-cost credits?
Yes. Seller contributions are generally negotiable, subject to the parties' agreement and applicable financing requirements. Sellers may accept, reject, or counter an offer, consistent with applicable law and their contractual obligations.
Can an offer fall through after it's accepted?
Yes. Depending on the contract and circumstances, issues involving attorney review, inspections, financing, appraisal, title, or other conditions may prevent a transaction from reaching closing.
This article provides general real estate information and is not legal, mortgage, tax, or financial advice. Every transaction is different. Buyers and sellers should consult their New Jersey real estate attorneys, lenders, and other qualified professionals regarding the terms of their particular transaction.
Recent Posts