5 Things You Can Negotiate When Buying a House in New Jersey (Besides the Price)
When you find a home you love in New Jersey, it's natural to focus on one question: How much should we offer?
But the purchase price isn't the only part of a real estate transaction you may be able to negotiate.
Depending on the seller's circumstances, the home's condition, current market competition, and your financing, there may be opportunities to negotiate terms that make buying the home more affordable, more convenient, or less stressful.
In some cases, a seller contribution toward closing costs may be more helpful than a small price reduction. In others, a repair agreement or flexible closing date could make a meaningful difference.
Here are five things New Jersey homebuyers should understand before submitting their next offer.
What Can You Negotiate When Buying a House in New Jersey?
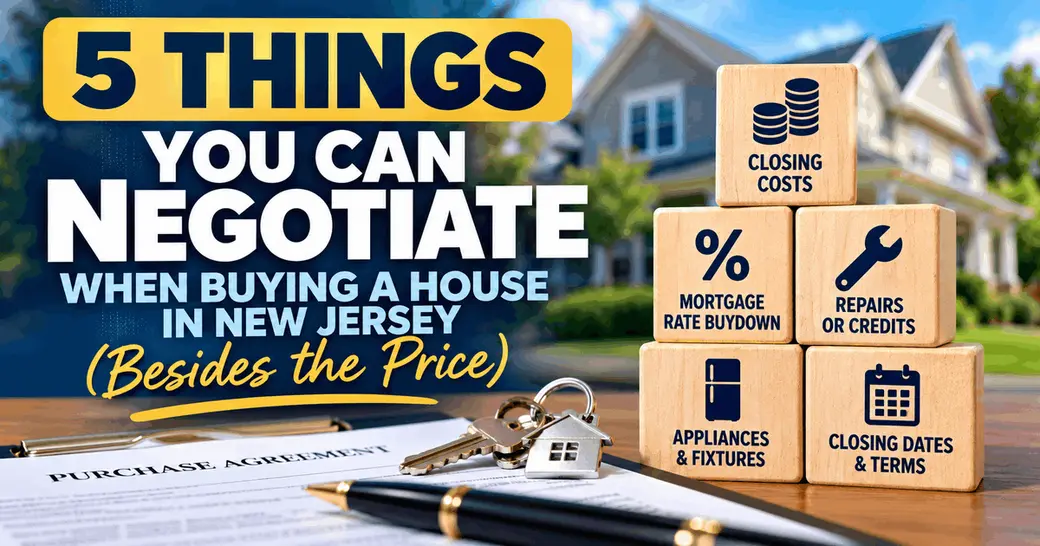
Besides the purchase price, buyers may be able to negotiate seller contributions toward closing costs, mortgage interest-rate buydowns, inspection-related repairs or credits, included appliances and fixtures, and the closing or occupancy timeline.
These terms are not guaranteed. The seller must agree, and some concessions are subject to mortgage lender requirements, appraisal considerations, and the final contract.
The goal isn't to ask for everything. It's to identify the terms that matter most to you and structure an offer that makes sense for both sides.
1. Ask the Seller to Contribute Toward Your Closing Costs
Many buyers save carefully for their down payment but underestimate the additional money required to complete a home purchase.
Depending on the transaction, buyer closing expenses may include:
- Mortgage lender and appraisal fees
- Title-related expenses and title insurance
- Attorney fees
- Prepaid homeowners insurance
- Property tax escrows and other prepaid expenses
- Other settlement and financing charges
One possible negotiating strategy is to ask the seller to contribute toward eligible closing expenses. This is commonly called a seller concession or seller credit.
Example: A $650,000 Home Purchase in New Jersey
Imagine you're buying a home in Edison for $650,000.
Your lender estimates that you'll need $15,000 for eligible closing costs and prepaid expenses, in addition to your down payment.
Instead of negotiating only over the purchase price, you could ask the seller to contribute $10,000 toward those eligible expenses.
If the seller agrees and your lender approves the arrangement, that contribution could reduce the amount of cash you need to bring to closing.
However, it doesn't automatically mean you're getting a better overall financial deal. A seller may require a higher purchase price in exchange for a credit, and the home still needs to support the agreed price for financing purposes.
Important: Seller concessions are limited by loan-program rules and eligible expenses. They generally cannot be used as unrestricted cash back or to fund a buyer's required down payment.
Before making an offer, ask your lender to compare the cash required at closing under different scenarios.
For more information, read our guide to closing costs when buying a home in New Jersey.
2. Negotiate Help With Your Mortgage Interest Rate
A lower mortgage payment can make a substantial difference in your monthly budget.
Some buyers are surprised to learn that seller contributions may sometimes be used toward an eligible mortgage interest-rate buydown.
There are two common approaches worth discussing with your lender.
Permanent Mortgage Rate Buydown
A permanent buydown generally involves paying discount points or other eligible financing costs to obtain a lower mortgage interest rate for the life of the loan.
If the seller agrees to contribute toward those costs, it may help you obtain a more favorable rate without paying the entire expense yourself.
Whether this is worthwhile depends on the cost, the rate reduction available, how long you expect to keep the mortgage, and your overall financial situation.
Temporary Mortgage Rate Buydown
A temporary buydown, such as a 2-1 buydown, uses funds to temporarily reduce the portion of the mortgage payment paid by the borrower during an introductory period.
For example, under a typical 2-1 structure, the payment subsidy is calculated using an interest rate two percentage points below the note rate during the first year and one percentage point below during the second year.
After the temporary subsidy ends, the borrower pays the full scheduled amount based on the loan's note rate.
A temporary buydown does not permanently change the mortgage's contractual interest rate. Buyers also generally need to qualify under applicable underwriting requirements using the full note rate.
Should You Request a Rate Buydown or a Lower Price?
There is no universal answer.
A lower purchase price may reduce your loan balance and overall borrowing costs. A seller-funded buydown may improve the payment structure or reduce certain upfront financing expenses.
Ask your lender to compare:
- Cash needed at closing
- Monthly payment during any temporary buydown period
- Monthly payment after the subsidy ends
- Total interest and financing costs
- The break-even period for any permanent discount points
The best strategy depends on your financing and financial goals, not simply which option sounds more attractive.
3. Negotiate Repairs or Credits After the Home Inspection
A home inspection can reveal important information about a property's condition.
Depending on the contract, inspection findings, and negotiations, a buyer may request that the seller address certain issues before closing or agree to an appropriate financial adjustment.
Potential concerns might involve:
- Roof or active water intrusion problems
- Heating and cooling systems
- Electrical or plumbing defects
- Structural concerns
- Other significant conditions identified during due diligence
Should You Ask for Repairs or a Credit?
Suppose you're purchasing a home in Woodbridge and an inspection identifies a heating-system problem.
You may prefer the seller to arrange for a qualified contractor to make an agreed repair before closing.
Alternatively, you may prefer to negotiate an allowable credit or price adjustment and coordinate the work yourself after purchasing the property.
Each option has tradeoffs.
Seller-completed repairs may resolve an issue before you take ownership, but buyers should consider workmanship, documentation, and whether the work can be completed before closing.
A credit may offer more flexibility, but lender rules can restrict how credits are applied. Certain property conditions may also need to be addressed to satisfy appraisal, insurance, or mortgage requirements.
What If the House Is Being Sold As-Is?
An as-is sale generally means the seller is offering the property in its existing condition, subject to the specific terms of the contract.
It does not automatically answer every question about inspection rights, disclosure obligations, or whether a seller might consider a requested change.
However, buyers should never assume that an as-is seller will agree to repairs or credits.
Before signing, have your attorney explain the inspection provisions and the consequences of the agreement.
Related reading: What to Look for When Buying a House in New Jersey.
4. Negotiate Which Appliances and Other Items Stay With the Home
Not every item you see during a showing is automatically included in the sale.
Depending on the property and contract, buyers and sellers may negotiate items such as:
- Refrigerators, washers, and dryers
- Window treatments
- Certain light fixtures
- Outdoor equipment
- Other specifically identified personal property
Imagine finding a home in East Brunswick with a washer, dryer, and refrigerator that appear relatively new.
If those appliances are not included in the sale, replacing them could create an additional expense shortly after closing.
Rather than assuming they'll stay, your agent can help clarify what's included and, where appropriate, make those items part of the negotiation.
Put the Agreement in Writing
This is especially important when the seller plans to remove an item that a buyer might reasonably expect to remain.
The contract and any applicable addenda should clearly identify the items included or excluded.
Also, not every appliance or personal-property arrangement is treated the same way by mortgage underwriters. Your lender and attorney should review unusual inclusions or incentives.
Our advice: Don't wait until the final walkthrough to discover that an item you expected to remain has been removed.
5. Negotiate the Closing Date and Occupancy Terms
Sometimes the most valuable thing you can offer a seller isn't a higher price. It's a closing schedule that works with their plans.
For example, a homeowner selling in Metuchen may need time to coordinate the purchase of their next property.
Another seller relocating for work may prefer a faster closing.
If your circumstances allow some flexibility, that may help make your offer more attractive.
Closing Date Flexibility
Buyers and sellers can negotiate a proposed closing date, subject to the transaction's requirements.
Before agreeing, consider:
- Your lender's expected mortgage approval timeline
- Attorney review and inspection deadlines
- Appraisal and title requirements
- Your current lease or home-sale schedule
- The seller's moving arrangements
What About Letting the Seller Stay After Closing?
In some transactions, a seller may request permission to remain in the property for an agreed period after closing.
This type of arrangement requires careful legal consideration and should never be handled informally.
Your attorney and lender should review the proposed occupancy terms, insurance implications, possession arrangements, security provisions, and any other relevant risks.
Allowing post-closing occupancy is not appropriate for every buyer or financing program.
Our advice: Flexibility can be valuable, but only when the agreement protects your interests and fits your actual moving plans.
Which Negotiation Is Better: A Lower Price or Seller Concessions?
Let's look at a simplified example.
You're considering a home listed at $600,000, and the seller is open to negotiating.
| Offer strategy | Possible buyer benefit | Important consideration |
|---|---|---|
| $10,000 lower purchase price | Lower purchase price and potentially a smaller mortgage | May not reduce upfront closing expenses as much as a credit |
| $10,000 seller closing-cost contribution | May reduce cash needed for eligible closing expenses | Subject to lender limits, actual costs, and appraisal |
| Seller-funded rate buydown | May reduce eligible financing costs or mortgage payments | Actual benefit depends on the buydown structure and lender pricing |
| Agreed repair before closing | May address an important condition before ownership transfers | Scope, workmanship, timing, and documentation matter |
These are illustrative alternatives, not equivalent financial offers. A $10,000 price reduction and a $10,000 closing-cost credit can have very different effects on your cash needs, monthly payment, and long-term costs.
The right comparison should be based on your lender's actual figures and the property's market value.
How Negotiations Work in New Jersey
New Jersey home purchases commonly involve real estate agents, attorneys, lenders, inspectors, and title professionals.
For transactions using qualifying broker-prepared residential contracts, New Jersey's attorney review provisions may apply. The precise rights and deadlines depend on the contract and circumstances.
Once an agreement is reached, negotiated terms should be properly documented in the contract or appropriate addenda.
For more information, see our article What Is Attorney Review When Buying a House in New Jersey?.
Keep in mind that negotiating is not the same as winning every request. In a multiple-offer situation, extensive concessions may make an offer less attractive. In a less competitive situation, a seller may be more open to discussing alternative terms.
That's why the strongest strategy begins with understanding the individual property, the seller's priorities, and the buyer's financial goals.
How The Egri Team Helps New Jersey Buyers Negotiate With Confidence
Buying a home is about more than finding a property that looks good online.
It's about understanding its value, recognizing potential concerns, and deciding which contract terms are worth negotiating.
At The Egri Team, we help buyers throughout Middlesex County, Union County, and surrounding New Jersey communities evaluate homes and navigate the purchase process.
We can help you:
- Review comparable sales and determine a reasonable offer strategy.
- Understand a property's listing history and current competition.
- Identify potential negotiating opportunities.
- Coordinate with your lender to evaluate seller credits and financing options.
- Work with your attorney and other professionals throughout the transaction.
- Consider the full terms of an offer rather than focusing only on price.
If you're still searching for the right property, read our companion article: 5 Ways to Find a Better Deal on a Home in New Jersey.
Ready to Buy a Home in New Jersey?
Whether you're buying your first home or planning your next move, we'd be happy to help you explore your options.
Tell us the towns you're interested in, your preferred price range, and what matters most in your next home.
We'll help you evaluate available properties and develop an offer strategy that fits your goals.
Contact Chris & Diane Egri to Discuss Your Home Search
You can also explore available properties and helpful buyer resources at teamegri.com.
Frequently Asked Questions
Can you negotiate more than the price when buying a house?
Yes. Depending on the transaction, buyers may negotiate eligible seller contributions toward closing costs, certain repairs or credits, included items, and closing or occupancy terms. Mortgage financing rules and the seller's willingness to agree affect what's possible.
Can a seller pay closing costs in New Jersey?
Yes. A buyer can request a seller contribution toward eligible closing costs. The seller must agree, and the amount and use of the contribution must comply with the buyer's loan-program requirements.
Can you ask a seller to buy down your mortgage rate?
In some transactions, yes. Seller contributions may be used toward eligible temporary or permanent rate buydowns, subject to lender approval and financing guidelines. Ask your lender for a written comparison before deciding.
Can you negotiate repairs after a home inspection?
Depending on the contract, buyers may request repairs, a permitted credit, or another negotiated adjustment. The seller is not automatically required to agree, and the buyer's rights depend on the contract and applicable law.
Can you negotiate appliances when buying a home?
Yes. Buyers and sellers may agree on which appliances or other items are included in the sale. Any negotiated inclusions should be documented clearly in the contract and reviewed for financing implications where necessary.
Is it better to ask for a price reduction or a seller credit?
It depends on your down payment, closing costs, financing, and long-term plans. A lower price can reduce borrowing costs, while an eligible seller credit may reduce cash needed at closing. Your lender can compare both options.
Are seller concessions guaranteed in New Jersey?
No. Seller concessions are negotiated. The seller can accept, reject, or counter a request, and any agreement must also satisfy applicable contract and financing requirements.
This article is for general educational purposes and is not legal, tax, mortgage, or financial advice. Contract terms, financing rules, seller concessions, and negotiation opportunities vary. Consult your New Jersey real estate attorney, mortgage lender, and other qualified professionals regarding your specific transaction.
Recent Posts