What Happens After Your Offer Is Accepted on a House in New Jersey?
Getting an offer accepted on a home in New Jersey is exciting—but it is not the end of the home-buying process.
In many ways, it is the beginning of the next stage.
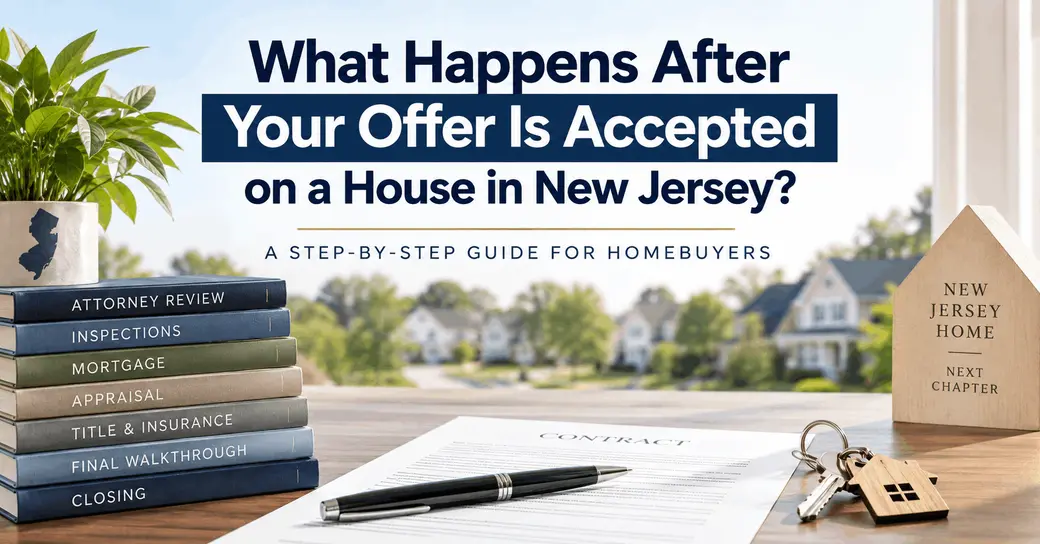
After the seller accepts your offer, there may still be attorney review, deposits, inspections, mortgage processing, an appraisal, title work, insurance requirements, a final walkthrough, and closing before the home officially becomes yours.
Understanding what happens after your offer is accepted can help you stay organized, meet important deadlines, and know what to expect as you move toward closing.
Here is a step-by-step look at what typically happens next when buying a home in New Jersey.
Step 1: The Contract Is Signed and Attorney Review Begins
One of the most important things New Jersey buyers should understand is that having your offer accepted is not necessarily the same as having a final contract.
In many New Jersey residential transactions involving a contract prepared by a real estate licensee, the buyer and seller have an opportunity to have attorneys review the signed contract.
For qualifying licensee-prepared residential contracts, the attorney-review provision provides a three-business-day review period. Saturdays, Sundays, and legal holidays are not counted, and the parties can agree in writing to extend the review period.
During attorney review, the attorneys may review the agreement, propose revisions, address contractual issues, or disapprove the contract within the applicable review period.
Because attorney review can affect important rights and obligations, buyers should send the signed contract to their attorney promptly and follow their attorney's legal guidance.
For a deeper explanation, read our guide to attorney review when buying a house in New Jersey.
Step 2: Make Sure Your Deposit Is Handled on Time
Your contract may require one or more deposits to be delivered according to specific terms and deadlines.
The amount, timing, and handling of deposits can vary by transaction and contract.
Do not assume that because your offer was accepted there is nothing else you need to do financially until closing.
Review the deposit requirements with your attorney and real estate professional and make sure you understand when funds are due and how they should be delivered.
Step 3: Move Forward With the Home Inspection
If your contract includes an inspection contingency or inspection rights, the next stage may include scheduling the appropriate inspections.
A professional home inspection can help you better understand the condition of the property and may identify issues involving areas such as:
- Structure and foundation
- Roofing
- Electrical systems
- Plumbing
- Heating and cooling systems
- Windows and doors
- Basement or crawl space
- Visible signs of moisture or other concerns
- Other property-specific conditions
Additional inspections or evaluations may also be appropriate depending on the property, contract, findings, and circumstances.
The inspection report does not automatically mean the seller must repair everything an inspector identifies.
Your rights, deadlines, and options depend on your contract. Discuss inspection findings with your real estate professional and obtain legal advice from your attorney regarding contractual rights or obligations.
Step 4: Your Mortgage Moves Into Processing and Underwriting
If you are financing the purchase, stay closely connected with your lender after the offer is accepted.
Preapproval was an important step before making the offer, but the lender still needs to complete the mortgage process for the specific property you are purchasing.
You may be asked to provide or update financial documentation such as:
- Pay stubs
- Bank statements
- Tax documents
- Employment information
- Information about assets or debts
- Explanations or documentation requested by the underwriter
Responding promptly to lender requests can help keep the mortgage process moving.
Buyers should also be cautious about making major financial changes while the loan is being processed. Before opening new credit, financing a vehicle, changing employment, moving large amounts of money, or making another significant financial decision, consider discussing it with your lender.
If you are still planning your overall purchase budget, our Mortgage Calculator and Home Affordability Calculator can help you explore the numbers.
Step 5: The Lender Orders the Appraisal
For financed purchases, the lender will generally order an appraisal as part of the mortgage process.
The appraisal helps the lender evaluate the property in connection with the loan being requested.
The appraisal is different from a home inspection.
A home inspection is primarily focused on helping the buyer understand the property's physical condition. An appraisal is performed for the lender and includes an opinion of value for lending purposes.
If the appraisal creates an issue, what happens next will depend on the contract, financing, applicable appraisal provisions, and the circumstances of the transaction.
Your lender, attorney, and real estate professional can each help within their respective roles if an appraisal issue arises.
Step 6: Title Work and Other Property Matters Are Reviewed
Before ownership can transfer, title and other transaction-specific matters need to be addressed.
The title process is intended to identify issues that could affect ownership or the transfer of the property.
Depending on the transaction, this stage may involve matters such as:
- Ownership records
- Existing liens
- Mortgages
- Judgments
- Other recorded interests or title issues
Your attorney and title professionals can explain the title process and any issues that arise in your particular purchase.
Step 7: Arrange Homeowners Insurance
Buyers using mortgage financing will generally need to obtain appropriate homeowners insurance before closing.
Do not wait until the last minute to start looking into coverage.
The property itself can affect insurance availability and cost, and additional coverage may be needed depending on the location and risks associated with the home.
For example, standard homeowners insurance generally does not cover flooding, so buyers should investigate flood risk and discuss appropriate coverage with a qualified insurance professional when relevant.
Your lender can tell you what insurance documentation it requires before closing.
Step 8: Continue Preparing for Your Cash to Close
Your down payment is not necessarily the only money you will need for the purchase.
Buyers may also need funds for closing costs, prepaid expenses, escrow funding, and other transaction-specific amounts.
As closing approaches, your lender and closing professionals will provide more detailed information about the funds required to complete the transaction.
If you are a first-time buyer or still planning your purchase, our guide to how much money you need to buy your first home in New Jersey explains the broader savings picture.
You can also read our detailed guide to closing costs when buying a home in New Jersey.
Step 9: Keep Track of Contract Deadlines and Contingencies
Once your offer is accepted, several parts of the transaction can be moving at the same time.
Your contract may contain deadlines or requirements involving:
- Attorney review
- Deposits
- Inspections
- Mortgage financing
- Appraisal
- Title matters
- Closing
- Other negotiated contingencies or obligations
Missing an important contractual deadline can create problems, so communication is critical.
Your real estate professional can help coordinate the transaction, your lender handles the mortgage process, and your attorney should advise you regarding legal and contractual matters.
Step 10: Review Your Final Loan and Closing Information
As the mortgage and transaction move toward completion, your lender and closing professionals will provide important documents and final figures.
Review documents carefully and ask questions about anything you do not understand.
This is also the time to confirm how your required closing funds must be delivered.
Because real estate transactions can involve significant wire transfers, buyers should take wire-fraud precautions seriously. Independently verify wiring instructions with the appropriate trusted closing professional using a known telephone number before sending funds.
Step 11: Complete the Final Walkthrough
Shortly before closing, buyers generally have an opportunity to conduct a final walkthrough of the property.
The final walkthrough is not another full home inspection.
It is an opportunity to confirm the property's condition before closing and, depending on the transaction, verify matters such as whether the seller has moved out and whether agreed-upon work has been completed.
If you notice a significant issue during the walkthrough, raise it promptly with your real estate professional and attorney rather than waiting until after closing.
Step 12: Close on Your New Jersey Home
Closing is when the transaction reaches its final stage.
The necessary documents are completed, funds are handled, the lender's requirements are satisfied, and ownership of the property is transferred according to the transaction.
Once the closing requirements are completed and you are authorized to take possession, you can officially begin the next chapter as a homeowner.
Getting from an accepted offer to closing involves many moving parts, but understanding the process ahead of time can make each stage much easier to navigate.
How Long Does It Take to Close After an Offer Is Accepted in New Jersey?
There is no single closing timeline that applies to every New Jersey home purchase.
The timing can depend on factors such as:
- The closing date negotiated in the contract
- Attorney review
- Inspection timelines
- Mortgage processing and underwriting
- Appraisal
- Title work
- Contract contingencies
- Property-specific issues
- Whether the buyer or seller needs to coordinate another transaction
Instead of relying on a general rule, buyers should pay attention to the dates and requirements in their particular contract and stay in communication with the professionals handling the transaction.
Frequently Asked Questions About What Happens After an Offer Is Accepted in New Jersey
Is an accepted offer legally final in New Jersey?
An accepted offer does not necessarily mean every stage of the transaction is complete. In many New Jersey residential transactions involving a licensee-prepared contract, the signed contract is subject to an attorney-review provision. Buyers should consult their attorney regarding the legal status of their specific contract.
What should I do first after my offer is accepted?
Make sure your attorney receives the signed contract promptly, stay in contact with your lender and real estate professional, understand any deposit requirements, and begin preparing for upcoming contractual deadlines such as inspections.
When should I schedule the home inspection?
The appropriate timing depends on your contract and attorney-review status. Inspection rights and deadlines are contractual matters, so coordinate with your real estate professional and follow your attorney's guidance regarding your specific transaction.
When does the appraisal happen?
For a financed purchase, the lender generally orders the appraisal during the mortgage process after the property is under contract. Timing can vary by lender and transaction.
Can my mortgage still be denied after my offer is accepted?
Yes. A preapproval is not the same as final loan approval. The lender still needs to process and underwrite the loan, evaluate required documentation, review the property and appraisal, and determine whether its lending requirements have been satisfied.
Should I make large purchases after my offer is accepted?
Be cautious about major financial changes while your mortgage is being processed. New debt, credit inquiries, large transfers, or employment changes may affect the lending process. Discuss significant financial decisions with your lender before taking action.
What is the final walkthrough for?
The final walkthrough gives the buyer an opportunity shortly before closing to view the property again and confirm its condition and other transaction-specific matters before completing the purchase.
When do I get the keys to my new home?
Possession depends on the terms of the transaction and completion of the closing process. Your attorney and real estate professional can confirm when you are authorized to take possession and receive the keys.
Buying a Home in New Jersey?
Getting your offer accepted is a major milestone—but there is still an important process between acceptance and receiving the keys.
Chris & Diane Egri and The Egri Team at Keller Williams Elite Realtors help New Jersey buyers navigate the real estate side of the transaction and coordinate with the attorneys, lenders, inspectors, title professionals, and other parties involved along the way.
Start with our New Jersey Home Buyer Guide, explore our First-Time Home Buyer resources, search homes for sale, or contact The Egri Team when you're ready to discuss your home-buying plans.
An accepted offer is worth celebrating. Knowing what happens next can help you move from contract to closing with greater confidence and fewer surprises.
This article provides general educational information about the New Jersey home-buying process and is not legal, tax, financial, insurance, or accounting advice. Real estate contracts and transactions vary. Buyers and sellers should consult the appropriate qualified professionals regarding their individual contract and circumstances.
Categories
Recent Posts